
Cheapest Insurance Cars at Chorley Group in 2026

Insurance is probably the last thing people think about when buying a car
If you’ve ever had that sinking feeling when an insurance quote lands in your inbox, you’re not alone. Car insurance in the UK has crept up over the last few years, and for many drivers the monthly payment now matters just as much as the cost of the car itself. That’s exactly why choosing a car that sits in a low insurance group can make such a big difference to your total running costs.
At Chorley Group, we work with real clients every day who want practical, affordable cars that don’t punish them with sky‑high premiums - whether they’re new drivers in their first year on the road, families adding a second car, or commuters looking to downsize to something more economical. In this blog, we’ll walk through how insurance groups work, which types of cars tend to be the cheapest to insure, and the kind of models you can find through Chorley Group that keep costs sensible without feeling stripped‑back.
Cheapest Insurance Cars at Chorley Group
Here are some of the new chapeast cars to insure from your favourite Chorley Group Brands.

Hyundai i10
Insurance group: 1-12 - The third instalment of the i10 range, the new Hyundai i10. Small on size, big on performance.

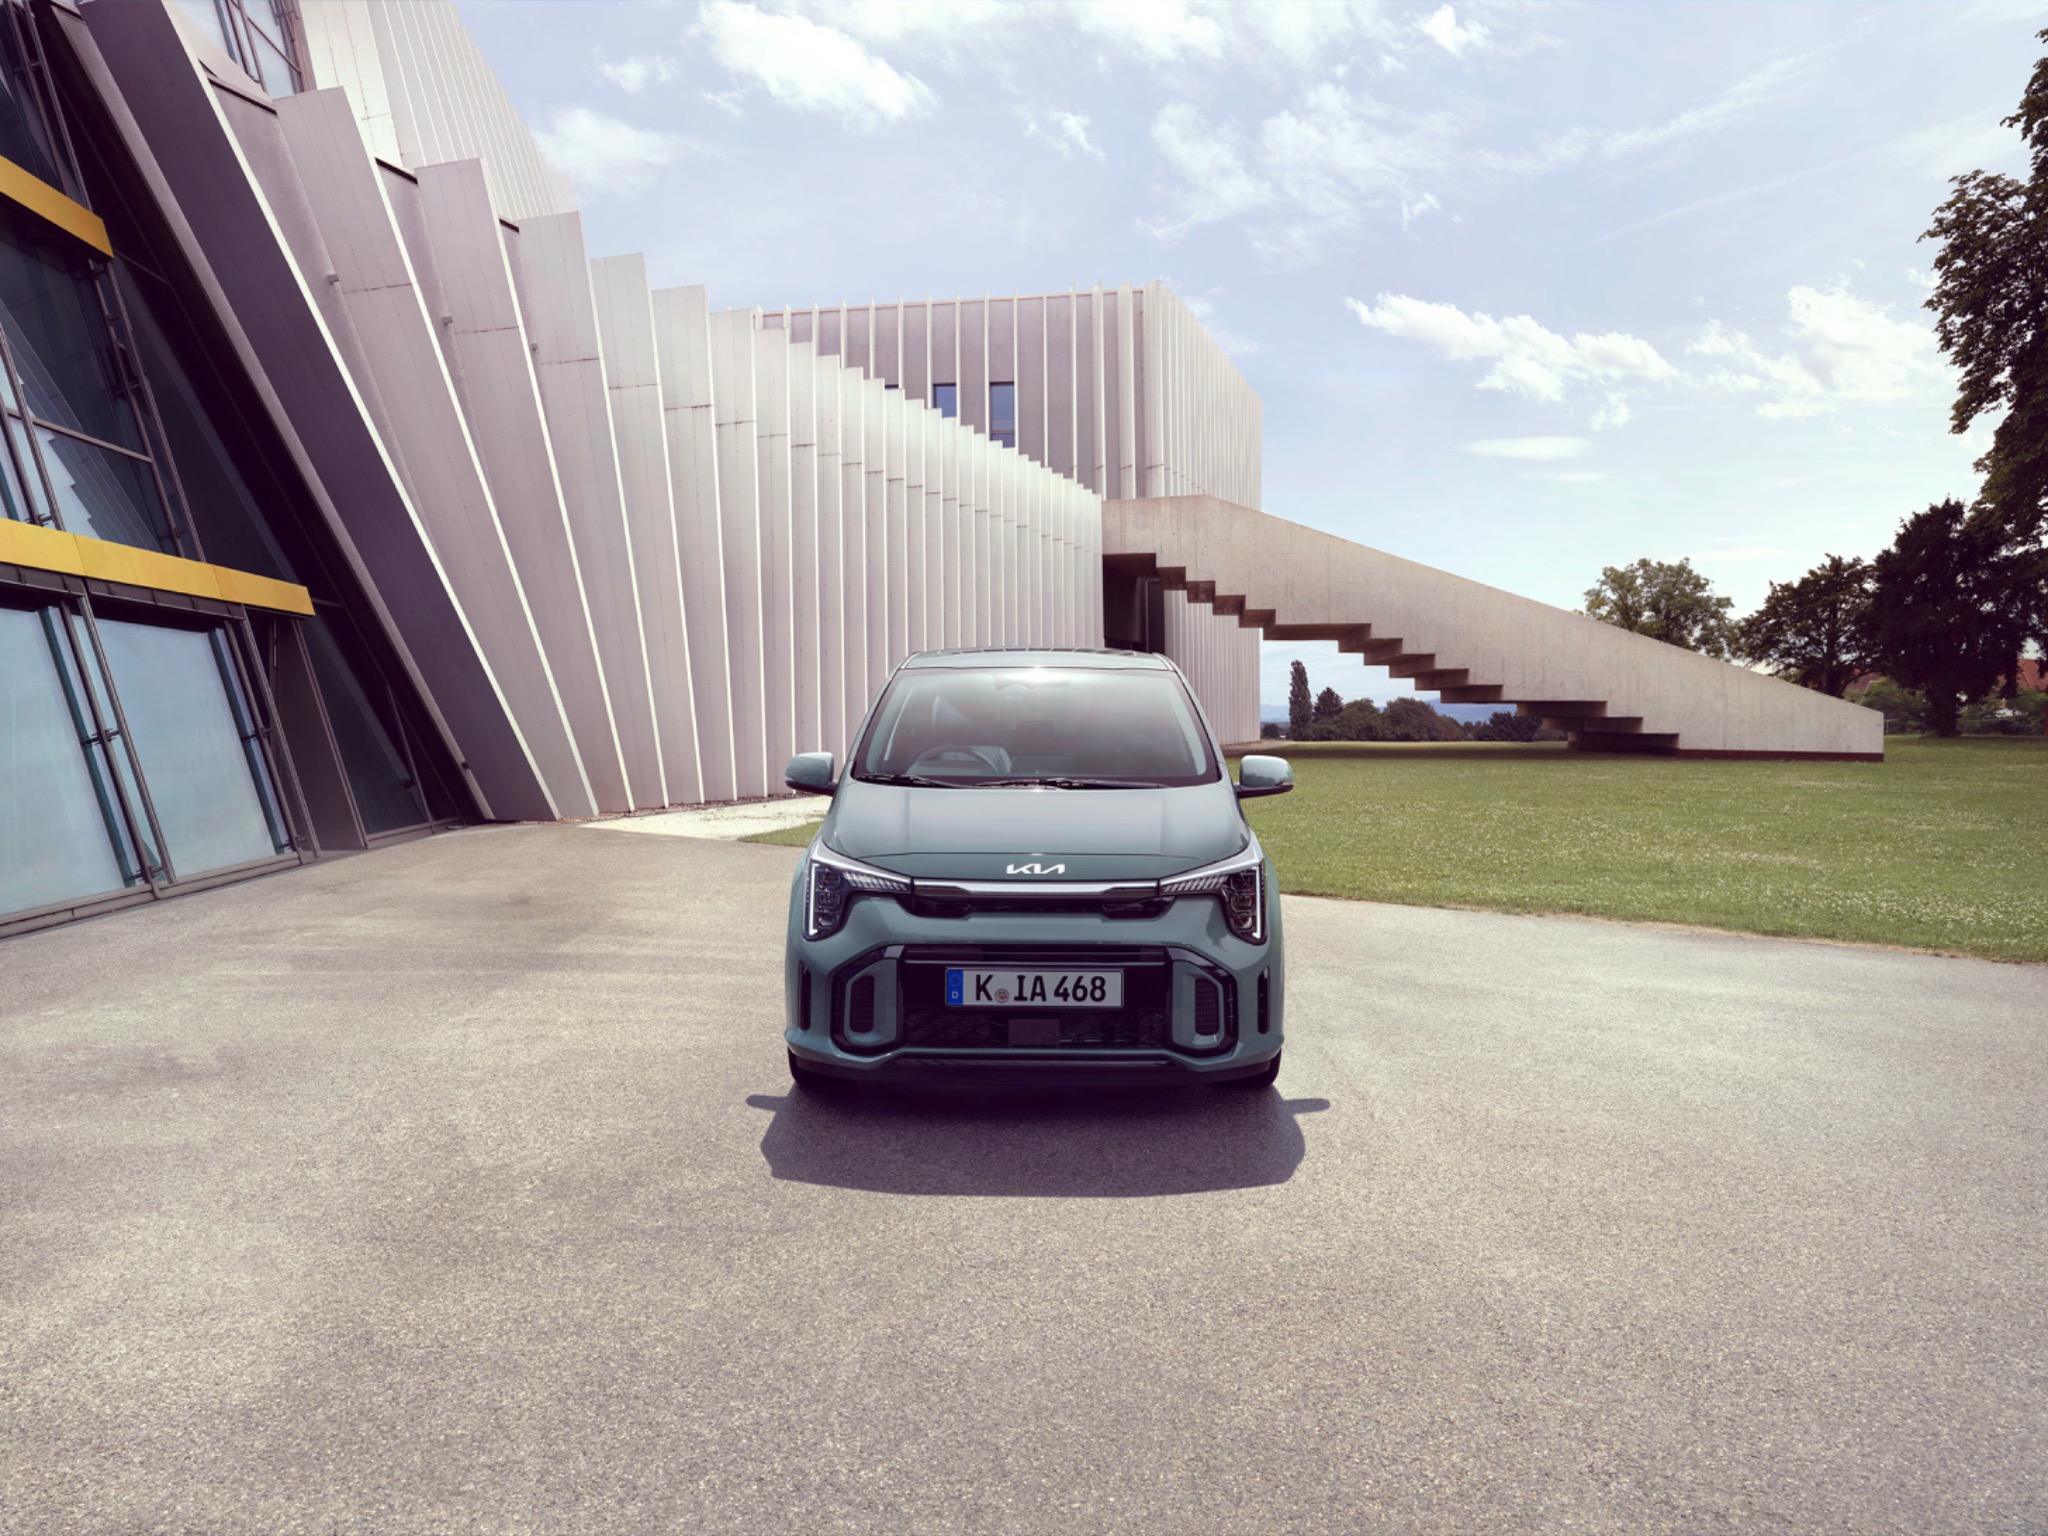
Kia Picanto
Insurance group: 1-12 - Even with its compact dimensions, the new Kia Picanto has one big personality. Ready to put a new spin on your own style.

Peugeot 208
Insurance group: 5-34 - The new PEUGEOT 208 has been reinvented: an irresistible sporty look, for a new, more modern signature.

MG3 Hybrid+
Insurance group: 4-24 - MG3 Hybrid+ represents a landmark in MG's powertrain development, as the first pure hybrid model to be launched.

Nissan JUKE
Insurance group: 8-26 - The Nissan Juke has been designed to make a statement, not just for you, the driver, but for everyone who watches in envy.
Cheap Cars to insurance in the UK
Everything you need to know about car insurance in the UK.
Before you start hunting for the “cheapest car to insure”, it helps to know what insurers are actually looking at. Every car sold in the UK is placed into an insurance group, currently numbered from 1 to 50. Lower‑numbered groups (1–10) are generally the cheapest to insure; cars in the highest groups tend to be more powerful, more expensive to repair, or more likely to be involved in high‑cost claims.
- Insurers and the group rating bodies look at things like:
- Purchase price/ parts cost (how expensive it is to repair or replace any parts on the car)
- Performance e.g. power, top speed, 0–60 time (basically, how tempting it is to drive quickly).
- Safety and security features for example: alarms, immobilisers, crash protection features.
- Repair times and complexity e.g. how long it typically sits in a garage or a bodyshop).
- Historical claims data for that specific model.
None of this means you must buy the absolute lowest group car available, but it does mean that choosing a model in a lower band can shave a noticeable amount off your annual premium, especially if you’re a younger or higher‑risk driver.
When you look at the cheapest‑to‑insure lists from major UK sites like Money Super Market or GoCompare, the same sort of car keeps appearing: small, modestly powered hatchbacks with a good safety record and inexpensive parts. They’re not always the flashiest things on the road, but they quietly get on with the job - exactly what insurers like.
Common features/traits of cars that are typically lead to cheap to insure include:
- Small engines (usually petrol), often between 1.0–1.2 litres with sensible power outputs (so no massive turbos)
- Five‑door hatchback bodies - practical and popular with new and family drivers.
- Good safety scores like NCAP 5* ratings and standard safety tech like airbags, ABS, and stability control.
- Strong reliability records, which help keep repair costs down over time. You can find this online depending on the manufacture.
- Wide availability of parts, making accident repairs faster and cheaper. This is usaully available on the big brands within the UK as the more of the cars on the road, the more parts available.
Guides from major UK car and insurance sites consistently underline that choosing the right engine and trim level within a model line‑up can be just as important as picking the model itself. Two versions of the same car can sit in very different insurance groups if one has a more powerful engine or expensive wheels and bodykit.
That’s why you so often see compact models from mainstream brands on “cheapest cars to insure” lists in the UK. They’re easy to live with, easy to fix, and not the typical choice for high‑risk driving.
You can speak to our team to learn more about the cars available at Chorley Group.
For new drivers, especially teenagers and people in their early twenties, insurance often costs more than the car itself in the first year or two (obviously depending on the car - of you get a 4lt petrol engine, your insurance for a new driver will be through the roof). Insurers price in a higher risk of accidents, and that’s where low‑insurance‑group cars are particularly valuable.
Benefits for getting a cheap to insure car for new and younger drivers include:
- More affordable first‑year premiums that make it realistic to get on the road.
- A better chance of building a no‑claims history without breaking the bank (no claims are so important to bring your insurance down year on year)
- Cars that are easier to handle, with modest power and good visibility.
- Lower running costs overall - fuel, tyres and servicing are often cheaper on these models too.
Many of the cars that appear on “cheapest cars to insure” lists across the interent are designed with exactly these drivers in mind, offering simple controls, strong safety kit and relatively low repair costs if something does go wrong. When you combine that with advice from a dealer who understands your situation, it becomes much easier to get onto the road with a manageable monthly outlay.


How to Start Your Search with Chorley Group - a little preparation goes a long way.
Find your next pre-owned car
Browse some of the pre-owned cars at our dealerships

- Electric
- Automatic
- 49,000 miles
- SILVER
Bolton Nissan
£148/MonthHP
£740 Deposit
£7,452
£7,449


1.0 IG-T Acenta Hatchback 5dr Petrol Manual Euro 6 (s/s) (100 ps)
Smartphone integration! Cruise
- Petrol
- Manual
- 42,101 miles
- White
Chorley Nissan
£152/MonthHP
£764.20 Deposit
£7,829
£7,691


2021 (71) MG MG3
Used1.5 VTi-TECH Exclusive Nav Hatchback 5dr Petrol Manual Euro 6 (s/s) (106 ps)
Sat Nav! Rear Camera! CarPlay!
- Petrol
- Manual
- 34,000 miles
- Silver
Chorley MG
Currently reserved
View similar to the 2021 (71) MG MG3


1.2 Griffin SUV 5dr Petrol Manual Euro 6 (s/s) (83 ps)
Cruise Control! Bluetooth! DAB
- Petrol
- Manual
- 27,306 miles
- Grey
Wigan Nissan
£168/MonthHP
£839.90 Deposit
£8,904
£8,448


1.2i Griffin Hatchback 3dr Petrol Manual Euro 6 (70 ps)
COMFORT SEATS! CRUISE! DAB!
- Petrol
- Manual
- 19,900 miles
- Blue
Blackpool Citroen
£170/MonthHP
£853.90 Deposit
£8,851
£8,588


0.9 IG-T N-Connecta Hatchback 5dr Petrol Manual Euro 6 (s/s) (90 ps)
*Sat Nav! Cruise! Bluetooth!*
- Petrol
- Manual
- 11,552 miles
- Grey
Wigan Nissan
Currently reserved
View similar to the 2017 (67) Nissan Micra


1.2 PureTech C-Series Edition Hatchback 5dr Petrol Manual Euro 6 (s/s) (83 ps)
HILL AST! PARK SNSRS! CRUISE!
- Petrol
- Manual
- 39,002 miles
- Beige
Bolton Citroen
Currently reserved
View similar to the 2022 (72) Citroën C3


1.5 Cooper Hatchback 3dr Petrol Manual Euro 6 (s/s) (136 ps)
DAB Radio! Keyless Start!
- Petrol
- Manual
- 37,000 miles
- White
Preston Nissan
£186/MonthHP
£929.80 Deposit
£9,347


1.2 PureTech C-Series Edition Hatchback 5dr Petrol Manual Euro 6 (s/s) (83 ps)
CRUISE! REAR CAM! 6 SPEAKERS!
- Petrol
- Manual
- 28,700 miles
- White
Bolton Citroen
£158/MonthPCP
£932.10 Deposit
£10,274
£9,370


1.2 PureTech Shine SUV 5dr Petrol Manual Euro 6 (s/s) (110 ps)
CRUISE! 3D NAV! PARK SENSORS!
- Petrol
- Manual
- 25,000 miles
- Grey
Blackpool Citroen
£168/MonthPCP
£943.30 Deposit
£10,151
£9,482
Hire Purchase representative example
- Monthly Repayments
- £147.54
- Cash Price
- £7,449
- Deposit
- £740
- Agreed Duration
- 60 months
- Purchase Fee
- £10
- Total Amount Of Credit
- £6,709
- Total Amount Payable
- £9,702.40
- Interest Rate (Fixed)
- 6.39%
- Representative APR
- 12.9%
- Interest Charges
- £2,243.40
Representative example: borrowing £6,709 over 60 months with a deposit of £740. 59 monthly payments of £147.54. Total amount payable £9,702.40. Representative APR 12.9%.
1
Choose the right car!
2
Add an experienced drivers
3
Improve security
4
Avoid car modifications
5
Improve your driving
6
Consider night curfews
7
Increase your excess
8
Black box insurance
Even picking the right car these days can be expensive to insure if everything else about your policy is set up in a way that makes insurers nervous. On the flip side, a few sensible decisions can help you get much more competitive quotes based on your circumstances.
Here are practical steps most UK drivers can consider:
- Choose a lower‑insurance model in the first place which we can help you with
- This is the big one! A car in a low insurance group gives you a head start before you’ve entered a single personal detail.
- Fit added approved security and park sensibly.
- Things like factory alarms, immobilisers, trackers or simple things like parking on a driveway rather than on the street can all help insurers know that your car is safe and less likely to be stolen or damaged.
- Adjust your annual mileage realistically
- Estimate your mileage honestly, but don’t overstate it “just in case” - insurers use mileage as a risk factor as you are using the car more and very high figures can push up your premium. We can help you work this out to make sure you have the correct amount based on your lifestyle.
- Consider a black box policy, especially for young drivers - this could be a big win!
- For careful drivers, especially under 25s, a telematics or Black Box policy that monitors driving behaviour can work out cheaper than a standard policy on the same car.
- Increase your voluntary excess (within reason)
- Agreeing to pay a slightly higher amount towards any claim can reduce your premium, as long as you’re comfortable with the excess if something goes wrong.
- Build and protect your no‑claims bonus
- Each year you drive claim‑free can reduce your premium; once you’ve built up several years of no‑claims, you can usually pay a little extra to protect it.
Just remember! None of these tricks replace the basics - keeping a clean licence, driving sensibly, and choosing a sensible car. But together they can make a notable difference to the price you pay each year.
Frequently asked questions about car insurance
Here are some of the most common questions we get asked about cheap car insurance.
Typically in the UK, the cheapest cars to insure are small, low‑power petrol hatchbacks from the top mainstream brands such as Hyundai, Kia and Citroen, often with engines around 1.0-1.2 litres and no performance‑orientated trim level.These types of car sit in lower bracket of insurance groups and are inexpensive to repair, which insurers love.
From what we usually see - Not always. Most new cars benefit from modern safety and security features that can reduce premiums, while certain used models sit in very low insurance groups because of their modest performance and older pricing. It usually comes down to the specific model, engine and trim rather than simply “new” versus “used”.
Yes and No! We can’t give formal insurance quotes as we do not offer insurance, but our sales teams can highlight models and engine options that are generally known to fall into lower insurance groups and the most popular cars with cost‑conscious drivers. We always recommend that you run your own quotes for any car you’re considering before you commit to a purchase.
For many careful drivers in the UK (especially new drivers or younger ones) a telematics or more commonly known as a Black Box policy can reduce insurance premiums compared with a standard policy on the same car. This is because the insurer can see you’re driving sensibly. However with a Black Box, if you drive aggressively or mostly at high‑risk times, it can work the other way and end up more expensive.
Yes. Non‑standard modifications such as larger alloy wheels, bodykits, performance upgrades or loud exhausts usually increase premiums because they can raise the risk of accidents or theft and increase repair costs. If you want to keep insurance low, it’s generally best to stick with a standard car or factory‑approved accessories.
Chorley Group can help you with the car itself, finance options and timing your purchase so you can get on the road quickly, but you’ll usually arrange your own insurance through your preferred provider or comparison site. We’re always happy to give you the car details you need to obtain accurate quotes before you sign for a vehicle.


